Christmas dinner and Christmas gifts for employees: tax, VAT and bookkeeping
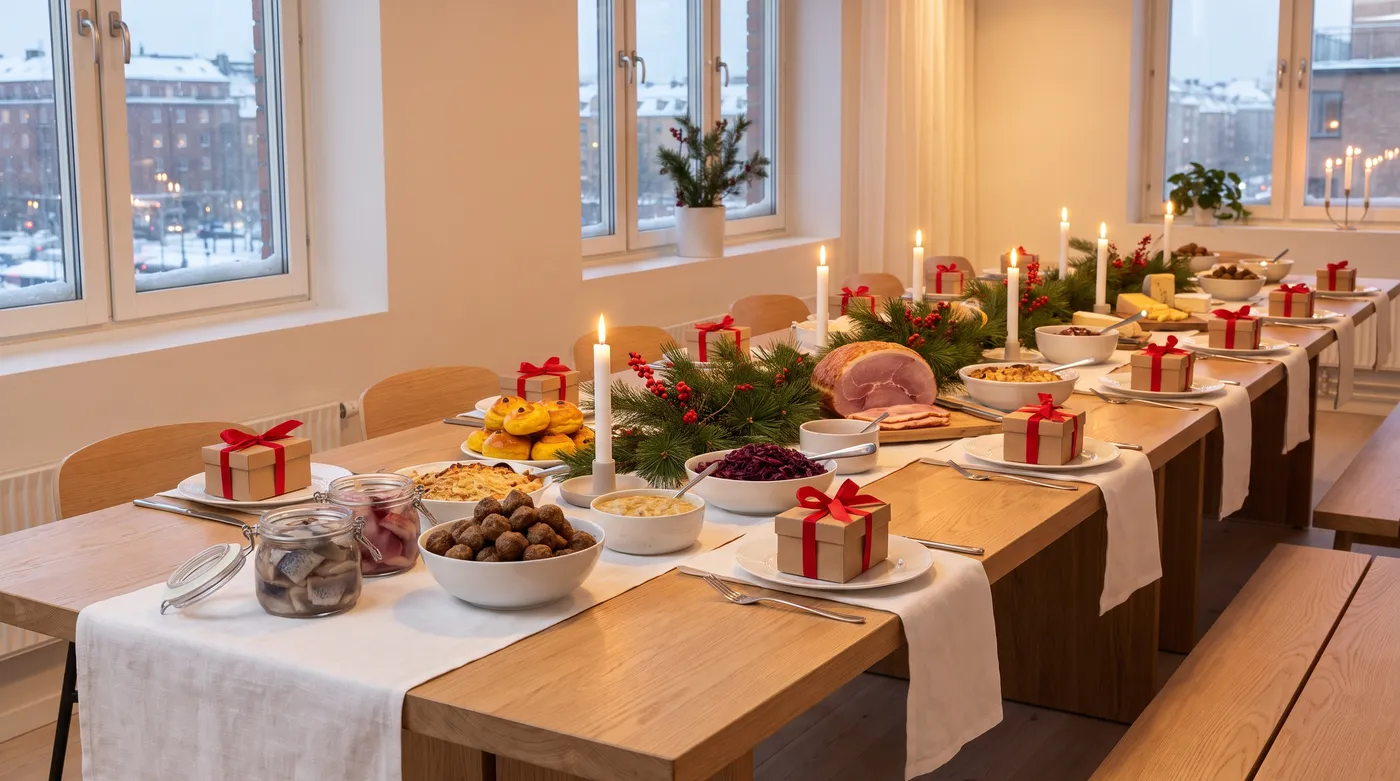
December is peak season for Christmas dinners (julbord), Christmas parties and Christmas presents for staff. It is also one of the most common sources of bookkeeping errors in the year: the food is booked as deductible, the Christmas gift ends up too expensive and VAT is deducted at the wrong amount. Here we go through the rules for 2026, from tax for employees to how to book the receipt.
Is the Christmas dinner tax-free for employees?
Yes. Meals provided by the employer are normally a taxable benefit, but a Christmas dinner or Christmas party counts as internal entertainment and is tax-free for employees. This also applies to any alcohol served.
As well as employees, contractors such as board members may take part. Employees' spouses or cohabiting partners and children living at home can also attend without being taxed on a benefit.
- Limited company where the owner is the only employee: the same rules apply as for other limited companies, so the owner can have a Christmas dinner without being taxed on a benefit.
- Sole trader (enskild firma): the person running the business is not an employee and is not covered by the rules on internal entertainment. If the business has employees, the rules apply to them.
Is the Christmas dinner deductible for the company?
Only partly. The company may claim deductions for no more than two staff parties per year, and the Christmas dinner counts as one of them. However, food and drink are not deductible for income tax purposes, except for simple refreshments such as coffee and a bun.
What is deductible are the associated costs, such as venue hire, music or entertainment. The deduction for these is capped at SEK 180 excluding VAT per person per occasion.
| Cost | Deduction for the cost | Deduction for the VAT |
|---|---|---|
| Food and drink at the Christmas dinner | No | Yes, on no more than SEK 300 excl. VAT per person |
| Associated costs (venue, music, entertainment) | Yes, no more than SEK 180 excl. VAT per person | Yes, on no more than SEK 180 excl. VAT per person |
| More than two staff parties per year | No | No |
How much VAT you can deduct
Even though the food is not deductible for income tax, a VAT-registered company may deduct the VAT on it. The deduction may not exceed the VAT on SEK 300 excluding VAT per person per occasion.
At a restaurant, food is taxed at 12 per cent and wine, spirits and strong beer at 25 per cent. If the Christmas dinner costs more than SEK 300 excluding VAT per person, the VAT deduction must be split according to what the food and drink actually cost. The simpler alternative is the standard amount set by the Swedish Tax Agency (Skatteverket):
- SEK 46 per person when the receipt only shows VAT at 12 and 25 per cent, i.e. a Christmas dinner at a restaurant with food and wine. This applies if the Christmas dinner costs at least SEK 300 excluding VAT per person and the receipt shows at least SEK 46 in VAT per person.
- SEK 33 per person when the receipt shows VAT at 6 and 25 per cent, for example if the food is bought as ready-made food without table service.
Not sure which VAT rate applies to the food? Read our guide to 6 or 12 per cent VAT.
Christmas gifts for employees: SEK 600 tax-free
A Christmas gift to employees is tax-free if its value does not exceed SEK 600 including VAT. It is the market value of the gift that counts, and your costs for administration and delivery are not included.
- Above the limit, the whole gift becomes taxable, from the first krona, and you pay employer contributions on the market value.
- All employees or a larger group of them must receive the gift for it to be tax-free.
- Cash is never tax-free. This also applies to gift cards that can be exchanged for cash. A gift card that cannot be exchanged for cash, on the other hand, can be a tax-free gift.
The gift is deductible for the company, whether or not it is taxable for the employee. You may deduct the VAT on the purchase as long as the gift is tax-free for the employee.
How to book the Christmas dinner and the Christmas gift
The BAS chart of accounts has separate accounts for staff entertainment. The deductible part is booked to 7631 and the rest to 7632.
| Account | Name in BAS | What is booked here |
|---|---|---|
| 7631 | Staff entertainment, deductible (Personalrepresentation, avdragsgill) | Associated costs up to SEK 180 excl. VAT per person |
| 7632 | Staff entertainment, non-deductible (Personalrepresentation, ej avdragsgill) | Food and drink, and associated costs above the limit |
| 2640 | Input VAT (Ingående moms) | The deductible VAT under the rules above |
| 7699 | Other staff costs (Övriga personalkostnader) | Tax-free Christmas gifts |
Example: Christmas dinner at a restaurant for ten employees
The restaurant invoices SEK 8 000 excluding VAT for food and wine, i.e. SEK 800 per person, with both 12 and 25 per cent VAT on the receipt. You choose the standard amount.
- 2640 Input VAT: SEK 460 (SEK 46 times ten people).
- 7632 Staff entertainment, non-deductible: the rest of the invoice, that is the total amount including VAT minus the SEK 460.
- Credit the company bank account or accounts payable with the invoice total.
Always note who attended and why on the receipt or invoice. Without a list of attendees and the purpose, it is hard to show that it was a staff party.
Checklist before the Christmas dinner
- Check that the Christmas dinner is one of no more than two staff parties during the year.
- Ask the restaurant to split food and drink with the correct VAT rate on the receipt.
- Write the list of attendees and the purpose on the supporting document.
- Keep the Christmas gift under SEK 600 including VAT, and give it to all employees or a larger group.
- Never give cash or gift cards that can be exchanged for cash as a Christmas gift.
- Book deductible and non-deductible amounts to separate accounts, and the VAT according to the rules above.
Would you rather not do the sums yourself?
We handle payroll and ongoing bookkeeping at a fixed price, so that Christmas dinners, gifts and benefits end up correctly both in the books and on the payslip. Do you run a restaurant? Read more about accounting for restaurants and our guide to the staff register (personalliggare) for restaurants ahead of the Christmas season. See our prices or request a quote below.
Sources
Frequently asked questions
Is a Christmas dinner deductible?
Food and drink are not deductible for income tax purposes, but associated costs such as the venue and music are deductible up to SEK 180 excluding VAT per person. The VAT on the food may be deducted on no more than SEK 300 excluding VAT per person per occasion.
How expensive can a tax-free Christmas gift be?
No more than SEK 600 including VAT. If the gift costs more, its whole value becomes taxable for the employee, from the first krona.
How many staff parties per year are deductible?
No more than two. The Christmas dinner counts as one of them.
Which account do you book a Christmas dinner to?
In BAS, 7631 Staff entertainment, deductible is used for deductible associated costs and 7632 Staff entertainment, non-deductible for food and drink. The VAT is booked to 2640 Input VAT.
Can you give a gift card as a Christmas present?
Yes, if the gift card cannot be exchanged for cash. Cash and gift cards that can be redeemed for cash are always taxable.
Get a price proposal for your company
Tell us what you need help with and we will come back with a proposal tailored to your needs.
- Free first meeting
- A fixed price before you decide
- No lock-in period
Call us on 031 - 52 40 00, weekdays 09:00 - 17:00. Or fill in the form and we will get back to you within 24 hours on weekdays.